Days the Ledger Cannot See: Aligning Invoice Due Dates With Real UK Payment Runs
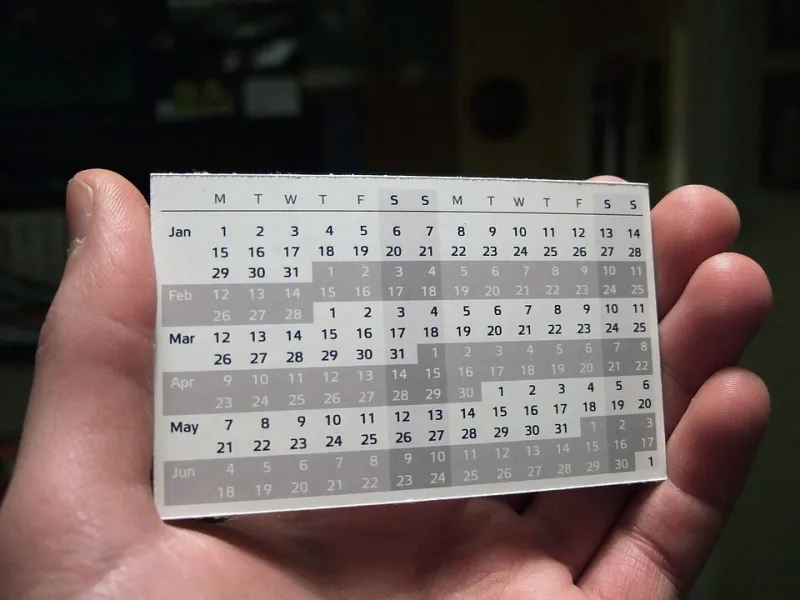
Photo: Joe Lanman from UK, CC BY 2.0, via Wikimedia Commons
An invoice can be contractually due on a date when no one at the buyer is able to pay it. That gap between the due date and the settlement date is one of the quieter causes of late payment in the UK. It is rarely visible in an aged-debt report, and it is seldom captured by a standard credit check. Yet it recurs every time a due date lands on a weekend, a public holiday, or after the cut-off for a buyer's weekly Bacs run.
For a supplier, the distinction matters. Cash-flow forecasts, the late-payment clock and the timing of a chase all rest on a date that may have been set without reference to how the buyer actually pays. A due-date audit is therefore not simply a review of contract wording. It is an exercise in reconstructing the buyer's payment calendar.
The contractual date is not the settlement date
Most UK terms are written as a number of days from invoice date or from receipt. Thirty days from 1 May produces 31 May on a calculator. But a due date is not a payment run. Settlement depends on invoice approval, the construction of the payment file, the rail used and whether the value reaches the bank before the relevant cut-off.
A buyer may operate a single weekly supplier run. In that model, an invoice approved on a Tuesday may not be included in a payment file until Thursday, and the file may not settle until the following week. The contractual date can pass in the meantime. The supplier sees a late payment; the buyer sees a payment made on the first available run. Both statements can be true, which is why the operational calendar deserves a place in the credit file alongside the written terms.
Weekends and bank holidays
A due date that falls on a Saturday or Sunday is a common source of quiet delay. Some contracts address the point expressly. Others do not. Even where the contractual position is clear, the practical position is usually that the buyer's finance team will process the payment on the next working day or the next scheduled run.
The UK does not have a single bank holiday calendar. England and Wales, Scotland and Northern Ireland observe different dates. A supplier with customers across the UK should not assume that one holiday list covers every buyer. A date that is a normal working day in London may be a public holiday in Edinburgh, and a payment run scheduled for that date may not happen.
The sensible response is to keep two dates in the ledger: the contractual due date and the expected operational settlement date. The first protects the supplier's legal position. The second supports forecasting and tells the credit controller when to act. The two should not be merged. Overwriting the contractual date with the operational date can weaken a later claim and distort the late-payment clock.
The Bacs cut-off and the weekly run
Bacs is not an instant transfer. It operates on a three-day cycle, and a payment file submitted after the buyer's bank cut-off moves into the next cycle. A buyer that runs Bacs once a week can therefore add several days after the contractual due date without any individual invoice being disputed.
Suppliers should ask new customers a small set of practical questions before the first invoice is raised: how often supplier payments are run, which day the file is built, what the bank cut-off is, and whether the buyer uses Bacs, Faster Payments or CHAPS for supplier payments. The answers belong in the customer record. They are as relevant to cash-flow planning as the agreed credit limit.
Faster Payments is often treated as a solution, but it is not a substitute for a calendar. Many buyers still apply daily cut-offs, approval limits and fraud checks. A payment can leave the buyer's bank quickly and still arrive after the contractual date because the file was approved late. CHAPS has its own cut-off and cost profile, so it is usually reserved for larger or urgent payments.
Rebuilding the due date around the payment run
A practical audit starts with the last three months of settled invoices. For each customer, compare the contractual due date with the date cash actually arrived. Where the gap is consistently a few days, the cause is often the payment run rather than a dispute. Where the gap is longer, the issue may be approval, missing purchase order references or a query that was never resolved.
The next step is to build a payment-run calendar for each significant customer. Mark the buyer's run days, the bank cut-off, the UK public holidays that affect the buyer's location, and the supplier's own month-end and quarter-end peaks. Then calculate an expected settlement date for each invoice. If the contractual due date falls after the cut-off or on a non-processing day, the credit controller should bring the chase forward rather than wait for the date to pass.
This is not about accepting later payment. It is about recognising where the contractual date and the operational date diverge, so that the supplier can press for inclusion in the earlier run. A short call before the run is built is often more effective than a formal letter sent after the date has passed.
A chasing timetable that respects the run
A useful timetable works backwards from the payment run, not forwards from the invoice date. Confirm receipt of the invoice before the buyer's approval deadline. Confirm that the invoice has been approved before the payment file is built. Ask for the remittance advice on the expected settlement date. If the payment is not included, ask which run it will join and record the answer.
Where the contractual date falls on a weekend or bank holiday, the supplier should decide in advance whether to chase on the last working day before the break or the first working day after it. The right answer depends on the buyer's run and the strength of the relationship, but the decision should be made deliberately rather than discovered when the cash fails to arrive.
The ledger discipline
A payment-run calendar is only useful if it is maintained. Review it monthly against actual receipts. Note which customers repeatedly settle after the run rather than on the due date. Use that pattern in cash-flow forecasts and in future credit terms. Where a buyer's payment practice is consistently later than the contractual term, the supplier has evidence for a conversation about terms, deposits or earlier invoicing.
The due date on the invoice is the date the contract creates. The date the cash arrives is the date the business can use. Prompt payment work sits between the two. Suppliers that map the gap are better placed to chase at the right moment, forecast with fewer surprises and keep the late-payment clock attached to the date the law and the contract provide.